All Categories
Featured

Why Automated Payment Systems Avoid Rating Drops
Table of Contents
Embracing Smart Financial Systems in Texas

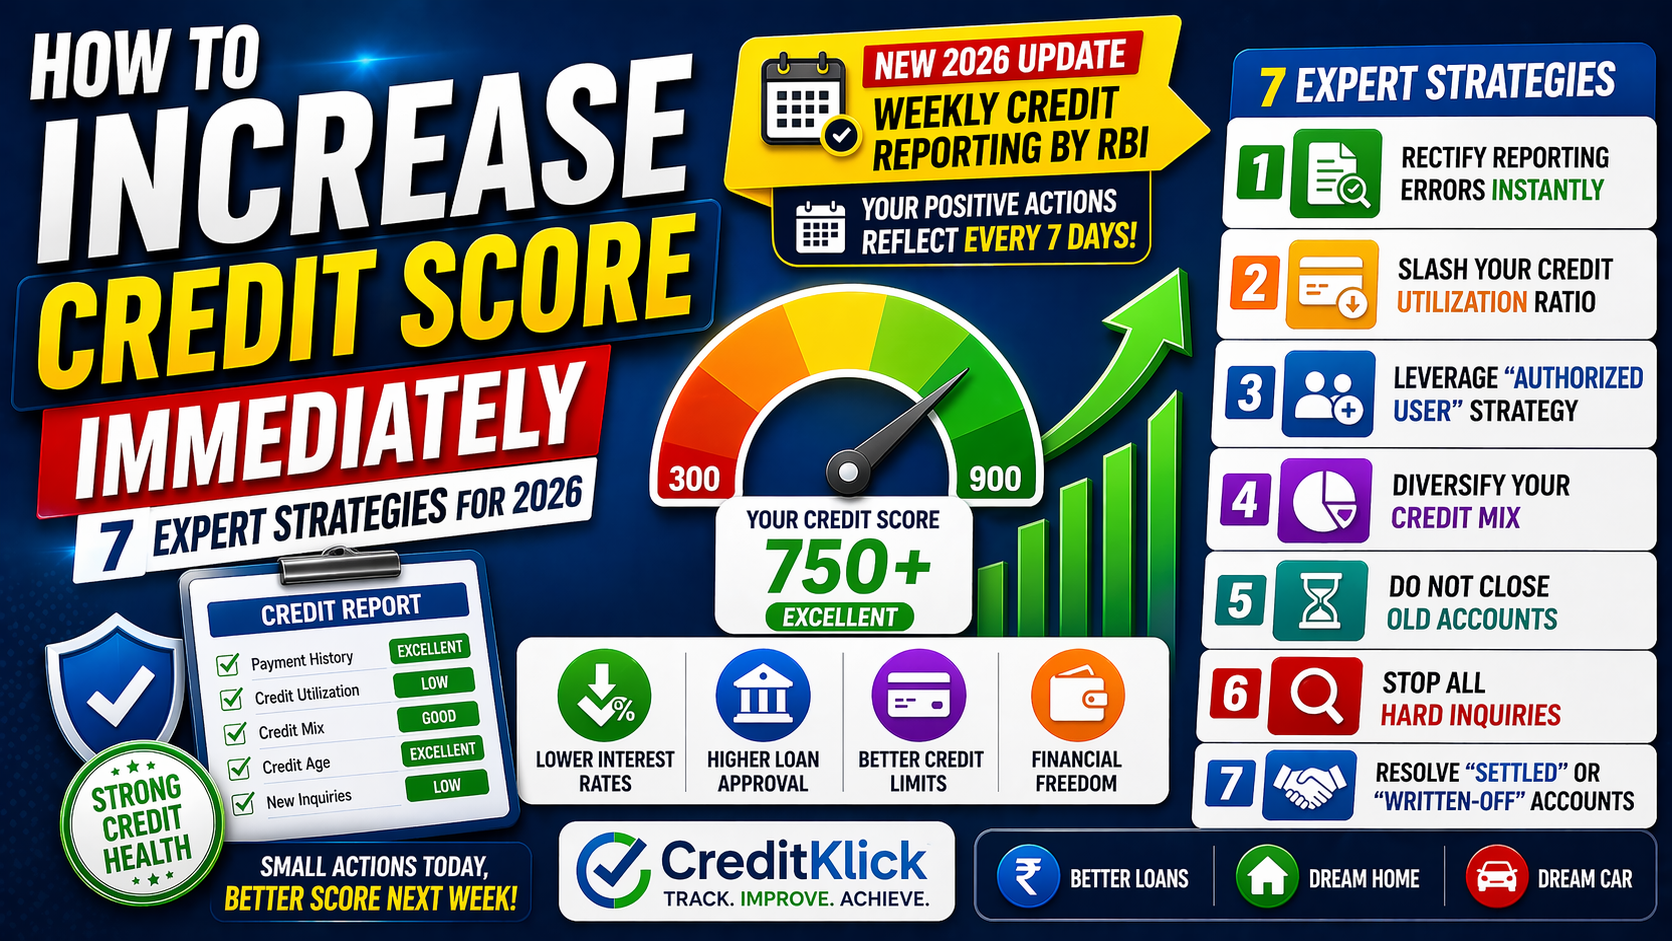
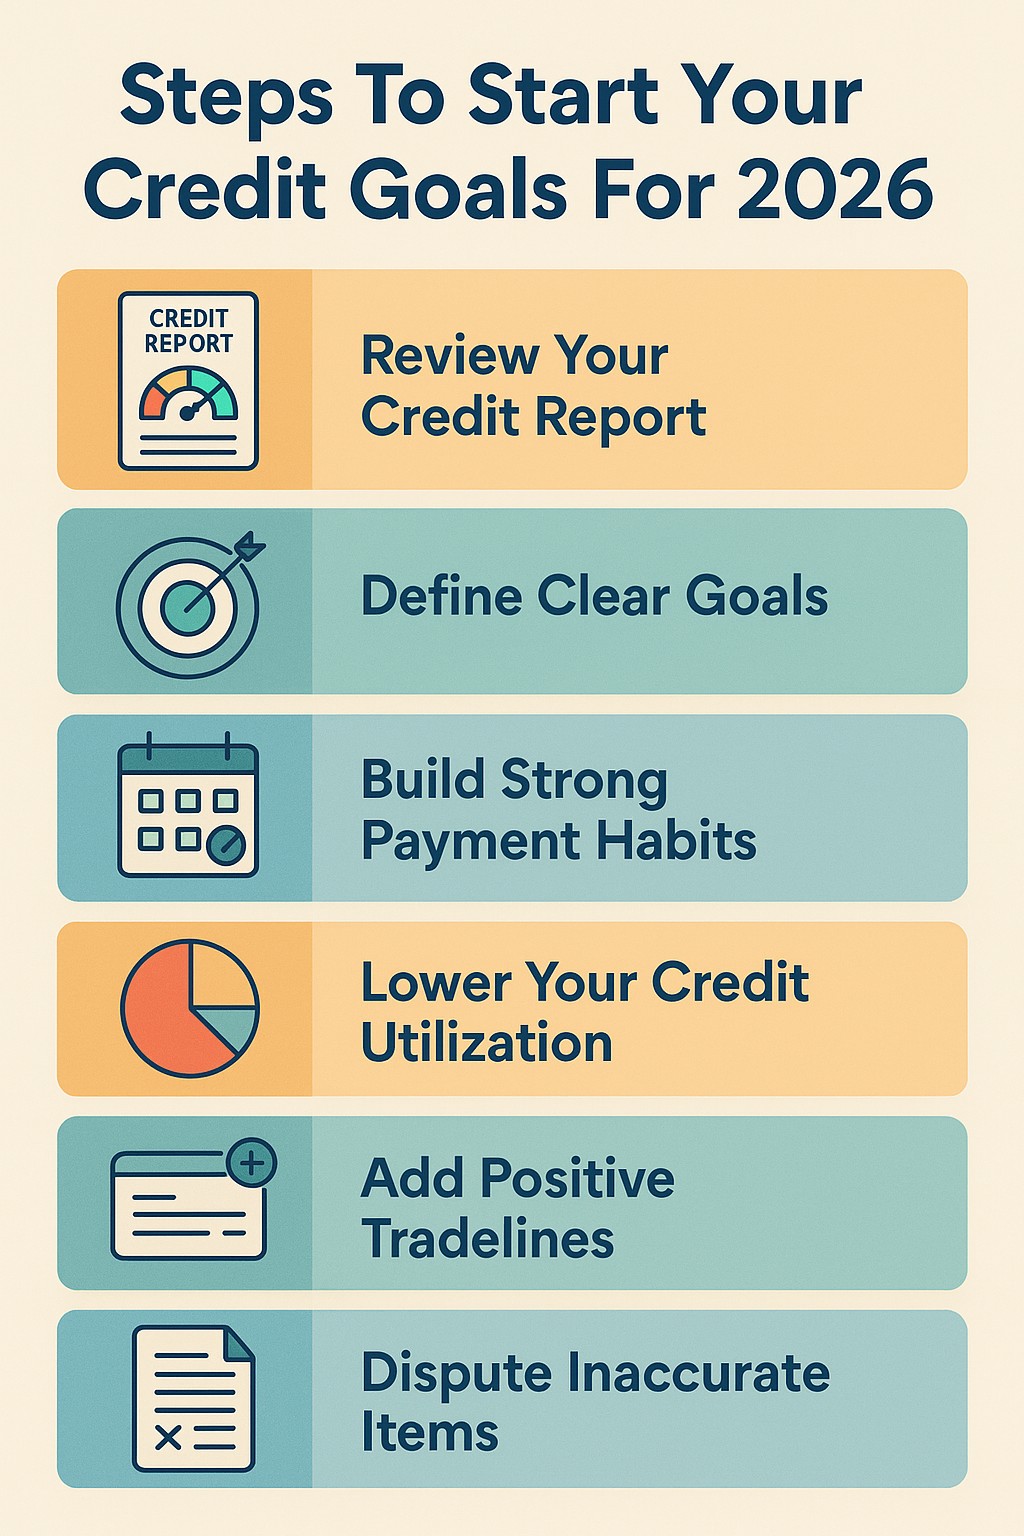
Financial management by 2026 has transitioned from manual record-keeping to highly advanced, self-governing systems. The reliance on paper declarations or manual calendar reminders has actually mostly faded as customers focus on efficiency and precision. Developing a strong credit profile in 2026 needs more than simply paying bills on time; it involves establishing a defensive architecture that avoids errors before they happen. Experts tracking patterns in Texas observe that locals who use automated oversight tend to maintain scores substantially greater than those who rely on memory.The core of this method depends on the synchronization of savings account, credit cards, and reporting companies. In the current year of 2026, banks supply sophisticated user interfaces that permit granular control over payment timing and quantity. Instead of simple "set it and forget it" models, modern-day automation utilizes predictive logic to ensure that payments are made when they most benefit the credit utilization ratio. This shift is particularly visible when looking at credit management programs, which now often incorporate straight with individual banking apps to supply real-time updates.Success in 2026 depends upon Financial Stress to guarantee that every financial action contributes favorably to a credit report. This approach minimizes the danger of human mistake, which remains a leading cause of unintentional rating drops. By removing the manual element, borrowers make sure that their credit rating reflects constant, accountable habits without the friction of monthly chores.
Advanced Autopay Methods for Texas
Basic autopay was when a blunt instrument that merely moved cash on a particular date. In 2026, professional monetary therapists suggest a tiered technique. The very first tier includes "Micro-Payments" or "Frequent Biking." Instead of one big payment at the end of the month, automated systems can be set to pay off small balances whenever they reach a particular limit. This keeps the reported balance low at all times, which is a major element in the credit report designs used throughout 2026. Wise Credit Card Usage deals clear paths for improvement by ensuring that credit usage remains listed below 10 percent. For lots of in Texas, high cost-of-living costs can result in high charge card balances if not handled daily. By automating numerous payments throughout the billing cycle, the reported utilization remains very little, even if the overall regular monthly costs is significant. This strategy is a staple of expert counseling techniques in 2026, permitting individuals to use their credit cards for rewards without the charge of high balance reporting.Another layer of this strategy involves "Buffer Automation." This is the practice of establishing secondary accounts that immediately cover any shortfalls in a main bank account. In 2026, these sweeps are rapid, avoiding "non-sufficient funds" mistakes that might result in missed out on payments. This protective step is frequently gone over by experts acquainted with local credit enhancement firms as a method to protect a perfect payment history versus unexpected bank delays or timing inequalities.
Incorporating AI-Driven Alerts and Changes

The year 2026 has actually seen the rise of AI assistants that do more than simply inform a user of an expense. These assistants now evaluate costs patterns and anticipate when a credit score may be at danger. If an automated subscription increases its cost suddenly, the system can flag it as a possible danger to a particular budget plan goal. This level of oversight is necessary for those browsing the complicated financial environment of Texas. Tracking services in 2026 have progressed to consist of "Artificial Fraud Security" and "Automated Dispute Filing." If an unapproved account appears on a credit report, automated systems can initiate the initial steps of a challenge before the user even logs in. This speed is important because credit scoring models in 2026 respond quickly to new information. A hold-up of a couple of days in reporting a mistake can lead to a rating drop that takes months to recover.Increased interest in Credit Usage for Consumers has actually forced lending institutions to be more transparent about how they report information. Debtors who utilize automated tools to examine their own reports find that they can catch inconsistencies that manual reviews often miss. These tools compare the data across all three significant bureaus and highlight any disparities in payment history, account age, or credit line. In Texas, where competitors for low-interest loans is high, having a tidy and accurate report is a requirement instead of a high-end.
Credit Mix and Automated Diversity
A healthy credit profile in 2026 requires a diverse mix of account types. While many individuals focus solely on charge card, scoring models also search for installment loans, such as automobile loans or personal loans. Counselors frequently recommend utilizing automated "Credit Home builder Loans" for those who need to diversify their mix without taking on high-interest financial obligation. These products automatically subtract a small amount each month, hold it in a secured account, and report the on-time payments to the bureaus.In Texas, these automated builder tools are regularly coupled with credit consulting packages to offer a detailed method. The appeal of these systems is that they operate in the background. When the preliminary setup is complete, the customer can concentrate on their career or personal life while their credit history progressively climbs. This hands-off technique is the gold standard for financial health in 2026. Beyond installation loans, 2026 has introduced more methods to consist of non-traditional data in credit reports. Automation permits for the reporting of lease, energy, and even streaming service payments. Providers that focus on this data aggregation ensure that every on-time payment for a cellular phone expense or a home in Texas counts toward the final rating. For younger customers or those brand-new to the country, this automated addition of "soft" credit information is a primary method to develop a footprint.
Keeping Security in an Automated Environment
With increased automation comes the need for increased security. In 2026, financial therapy includes a heavy emphasis on digital hygiene. This indicates using encrypted password supervisors and two-factor authentication for each account linked to an automatic system. Professional consultants in Texas stress that while automation conserves time, it does not remove the requirement for routine human audits.A common recommendation is the "Quarterly Sync-Up." Every three months, a borrower must evaluate all automated triggers to ensure they still align with existing earnings and objectives. If a person receives a raise or changes jobs in 2026, their automatic payment thresholds must be changed accordingly. This ensures that the system continues to work for the person's current truth rather than their previous circumstances.Data personal privacy also stays an issue. When using digital financial tools, it is vital to understand what information is being shared and with whom. The policies of 2026 provide more security for consumers, however the obligation of selecting trustworthy platforms stays with the user. Looking for services that have a strong performance history of security within Texas is a sensible action before linking high-value accounts.
The Long-Term Effect of Financial Autonomy
The cumulative effect of these automated strategies is a more durable monetary standing. By 2026, the space in between those who use innovation to handle their credit and those who do not has actually broadened. The speed at which credit decisions are made-- often in seconds by AI lending institutions-- suggests that there is no longer any margin for mistake. A single late payment in 2026 can be more damaging than it was a decade earlier because the systems are more delicate to current data.Moving towards a fully automated design allows homeowners of Texas to move with more agility. Whether looking for a mortgage or an organization loan, having a credit report that is kept by an accurate, automatic system offers a level of self-confidence that manual tracking can not match. The expert techniques of 2026 highlight that credit is a tool to be handled with technical accuracy, not a secret to be feared.As the year 2026 progresses, the tools readily available for credit management will just become more integrated and intelligent. Embracing these changes is the most reliable way to guarantee long-lasting financial health. By setting up a system that prioritizes low usage, constant payments, and accurate reporting, anybody can achieve a top-tier credit rating. The shift toward automation represents a democratization of financial proficiency, putting the power of a professional counselor into the pocket of every consumer.

Latest Posts
Quick Credit Building Strategies 2026

Proven Ways to Fix My Credit 2026

A Guide to Improving Credit in 2026