All Categories
Featured
Building Credit Through Modern Financial Literacy Education
Table of Contents
Closing credit cards to "start fresh"Disregarding balances and hoping ratings fix themselvesApplying for multiple new accounts to offset debtThese relocations usually sluggish recovery instead of assisting it. If you're uncertain where to begin, you don't need to figure it out alone. Langley provides tools and resources to support much healthier credit habits, including: to help keep payments on timeSavings-building tools like the Educational covering credit, financial obligation, and financial fundamentals Vacation costs doesn't define your monetary future.
Vacation spending frequently impacts credit history through higher balances or missed out on payments Many credit report drops are short-term Paying for balances and staying consistent assists scores rebound Tools like Langley's Credit Builder Loan can support long-lasting healing.
Great credit can make it simpler to do anything from rent a home to receive a lower rate on a vehicle loan. On the other hand, bad credit can be a challenge to attaining your objectives. When your credit history is a barrier to the monetary life you desire, companies promising credit repair work might appear like heros.
Comparing Credit Repair Versus Counseling MethodsA Guide to Improving Credit in 2026
Credit repair business typically charge substantial charges to find and challenge negative information on your credit reports. Fortunately is you do not need to pay any person to fix your credit. You can repair your credit totally free by inspecting your credit report and taking steps to improve your credit report.
Inaccuracies in credit reports are rare but may appear from time to time, and depending on the details involved, could negatively impact your credit history. Examining your credit report from each of the 3 significant credit bureaus (Experian, TransUnion and Equifax) at least as soon as a year helps you spot issues.
Review your credit report for the following: Open credit accounts and accounts closed for up to 10 years appear on your credit report. Unreliable unfavorable information, even if it's simply a late payment that was actually paid on time, might reduce your credit score. Errors in individual details, such a name or address reported improperly by a creditor, won't affect your credit score but ought to still be fixed.
Once you file a conflict, Experian asks the company that provided the challenged details to examine their records. Incorrect information will be fixed; information that can't be confirmed will be deleted or upgraded.
Advantages of Professional Financial Counseling
Due to the fact that payment history is the biggest consider your credit score, even one late payment can lower your score. Late payments remain on your credit report for up to 7 years. If you're late but not yet 1 month behind on a payment, pay it instantly. If the payment is already 30 or more days overdue, bring the account current as soon as possible.
Can't pay for to make the payment? Contact the lending institution to inquire about hardship options. Payment history represent 35% of your FICO Rating, so once your accounts are all present, keep them that method by setting up autopay. You can generally establish autopay straight with the lending institution or service company or through the bank account you use to pay bills.
Ideally, however, you should pay the balance in complete each month. Ensure there's sufficient money in your account to cover all your autopays to avoid overdrafts or inadequate funds transactions. Your credit usage rate procedures how much revolving credit you're using relative to your overall credit limits. Credit utilization represent approximately 30% of your credit score.
Navigating New Credit Repair Laws for 2026
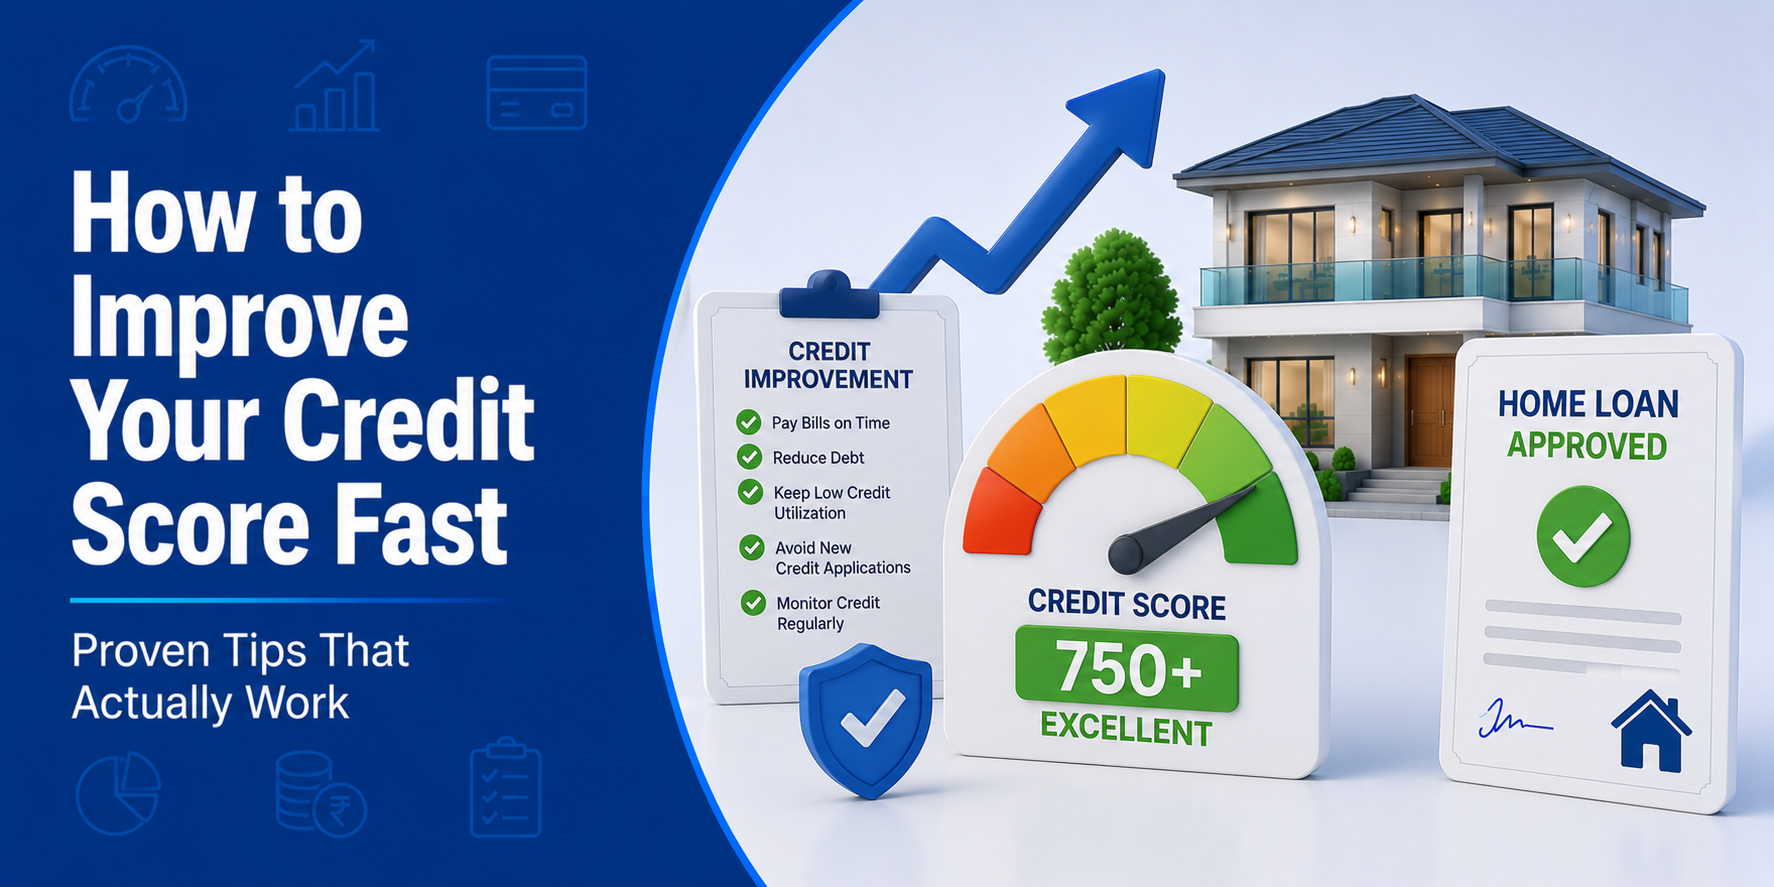
Do this for each card you hold and for the overall of all your credit cards. If your usage rate is 30% or more total or on a single account, pay for your charge card balances to see a prospective boost to your credit history. The lower your credit usage, the better.
Your info stays private. We'll find expenses with on-time payments, and you can add them to your Experian credit file. You'll learn right away if your credit history increased and by how lots of points. Results will vary. Not all payments are boost-eligible. Some users might not receive an improved rating or approval chances.

Discover more. If you're carrying debt balances, make a prepare for paying them down. Not just is high-interest debt pricey, however the quantity of debt you bring has an effect on your rating. Here are some concepts for how to pay off debt: Another choice is to consolidate your debt.

Latest Posts
Quick Credit Building Strategies 2026

Proven Ways to Fix My Credit 2026

A Guide to Improving Credit in 2026